Qantas Money Platinum:an 80k point trap?
Our Qantas Money Platinum (formerly Premier Platinum) review. The 80,000-point bonus, who gets it, the 3% overseas fee and whether the $399 fee pays.
G’day, points-hunters! Ever seen that shiny Qantas Money Platinum ad promising you the world? (Until recently it was sold as the Qantas Premier Platinum Mastercard, and it’s still the same Mastercard.) It’s one of the most visible cards in Australia, shouting about a massive sign-up bonus. It’s designed to be a “first-year powerhouse” for racking up points. But we’re here to answer the big question: is it a must-have travel hack, or does it have a serious “second-year problem” that makes it a $399 fee trap?
As always, we’ve done the deep dive, read the fine print and run the numbers so you don’t have to. Let’s get into it.
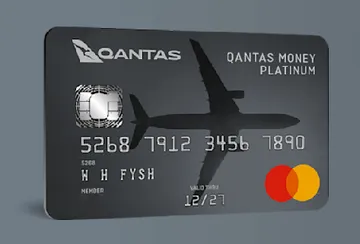
The big headline: up to 80,000 Qantas Points
This is the bait, and it’s a good one: a sign-up bonus of up to 80,000 Qantas Points. But “up to” is doing a lot of work here. The offer is deliberately split in two:
- Part 1 (the standard bonus): You get 40,000 bonus Qantas Points when you spend $5,000 on eligible purchases in the first 90 days.
- Part 2 (the “newbie” bonus): You get an additional 40,000 bonus points.
…but who really gets the full 80k bonus?
This is the first gotcha, and it’s a big one. That extra 40,000-point kicker is only for cardholders who haven’t earned Qantas Points on any credit or charge card in the 24 months before they apply. That’s right — not just a Qantas-branded card, but any co-brand card from Amex, ANZ, Westpac and others. It’s a deliberate anti-churning rule.
Here’s what that means for your “profit” in year 1, after the $349 reduced first-year fee:
- For the newbie (no Qantas-earning card in 24 months): you get the full 80k bonus plus 5k from spending = 85,000 points. We value that at about $1,275. After the $349 fee, you’re up by about $926. That’s a strong return.
- For the churner (you’ve had a Qantas-earning card recently): you get only the 40k bonus plus 5k from spending = 45,000 points. We value that at about $675. After the $349 fee, you’re up by about $326. Still positive, but a much thinner deal.
The earning engine: how it racks up points
The day-to-day earn rate is solid, with one major flaw:
- Domestic spend: 1 Qantas Point per $1 spent.
- International spend: 1.5 Qantas Points per $1 spent.
- Qantas spend: 1 additional Qantas Point per $1 (an effective 2 points per $1 on Qantas flights, which is very competitive).
The 1 point per $1 domestic rate is soft-capped at $10,000 per statement period (which is very generous!) before it halves to 0.5 points per $1.
Critical flaw: why you mustn’t use this card overseas
This is the most important piece of advice in this review. The card’s main marketing hook is that juicy 1.5 points per $1 on international spend. But buried in the fees table is a 3% foreign transaction fee.
Let’s do the simple, savvy-traveller maths:
- You spend $100 (AUD equivalent) overseas.
- Qantas Money charges you a $3.00 fee for the transaction.
- You earn 150 Qantas Points.
- At a good-value redemption (1.5 cents per point), your points are worth $2.25.
Are the perks worth the $399 ongoing fee?
After that $349 intro fee in year one, the card reverts to $399 every year after. A card with a high ongoing fee must provide high-value perks to justify its place in your wallet. Let’s see if these do.
Perk 1: two Qantas lounge invitations
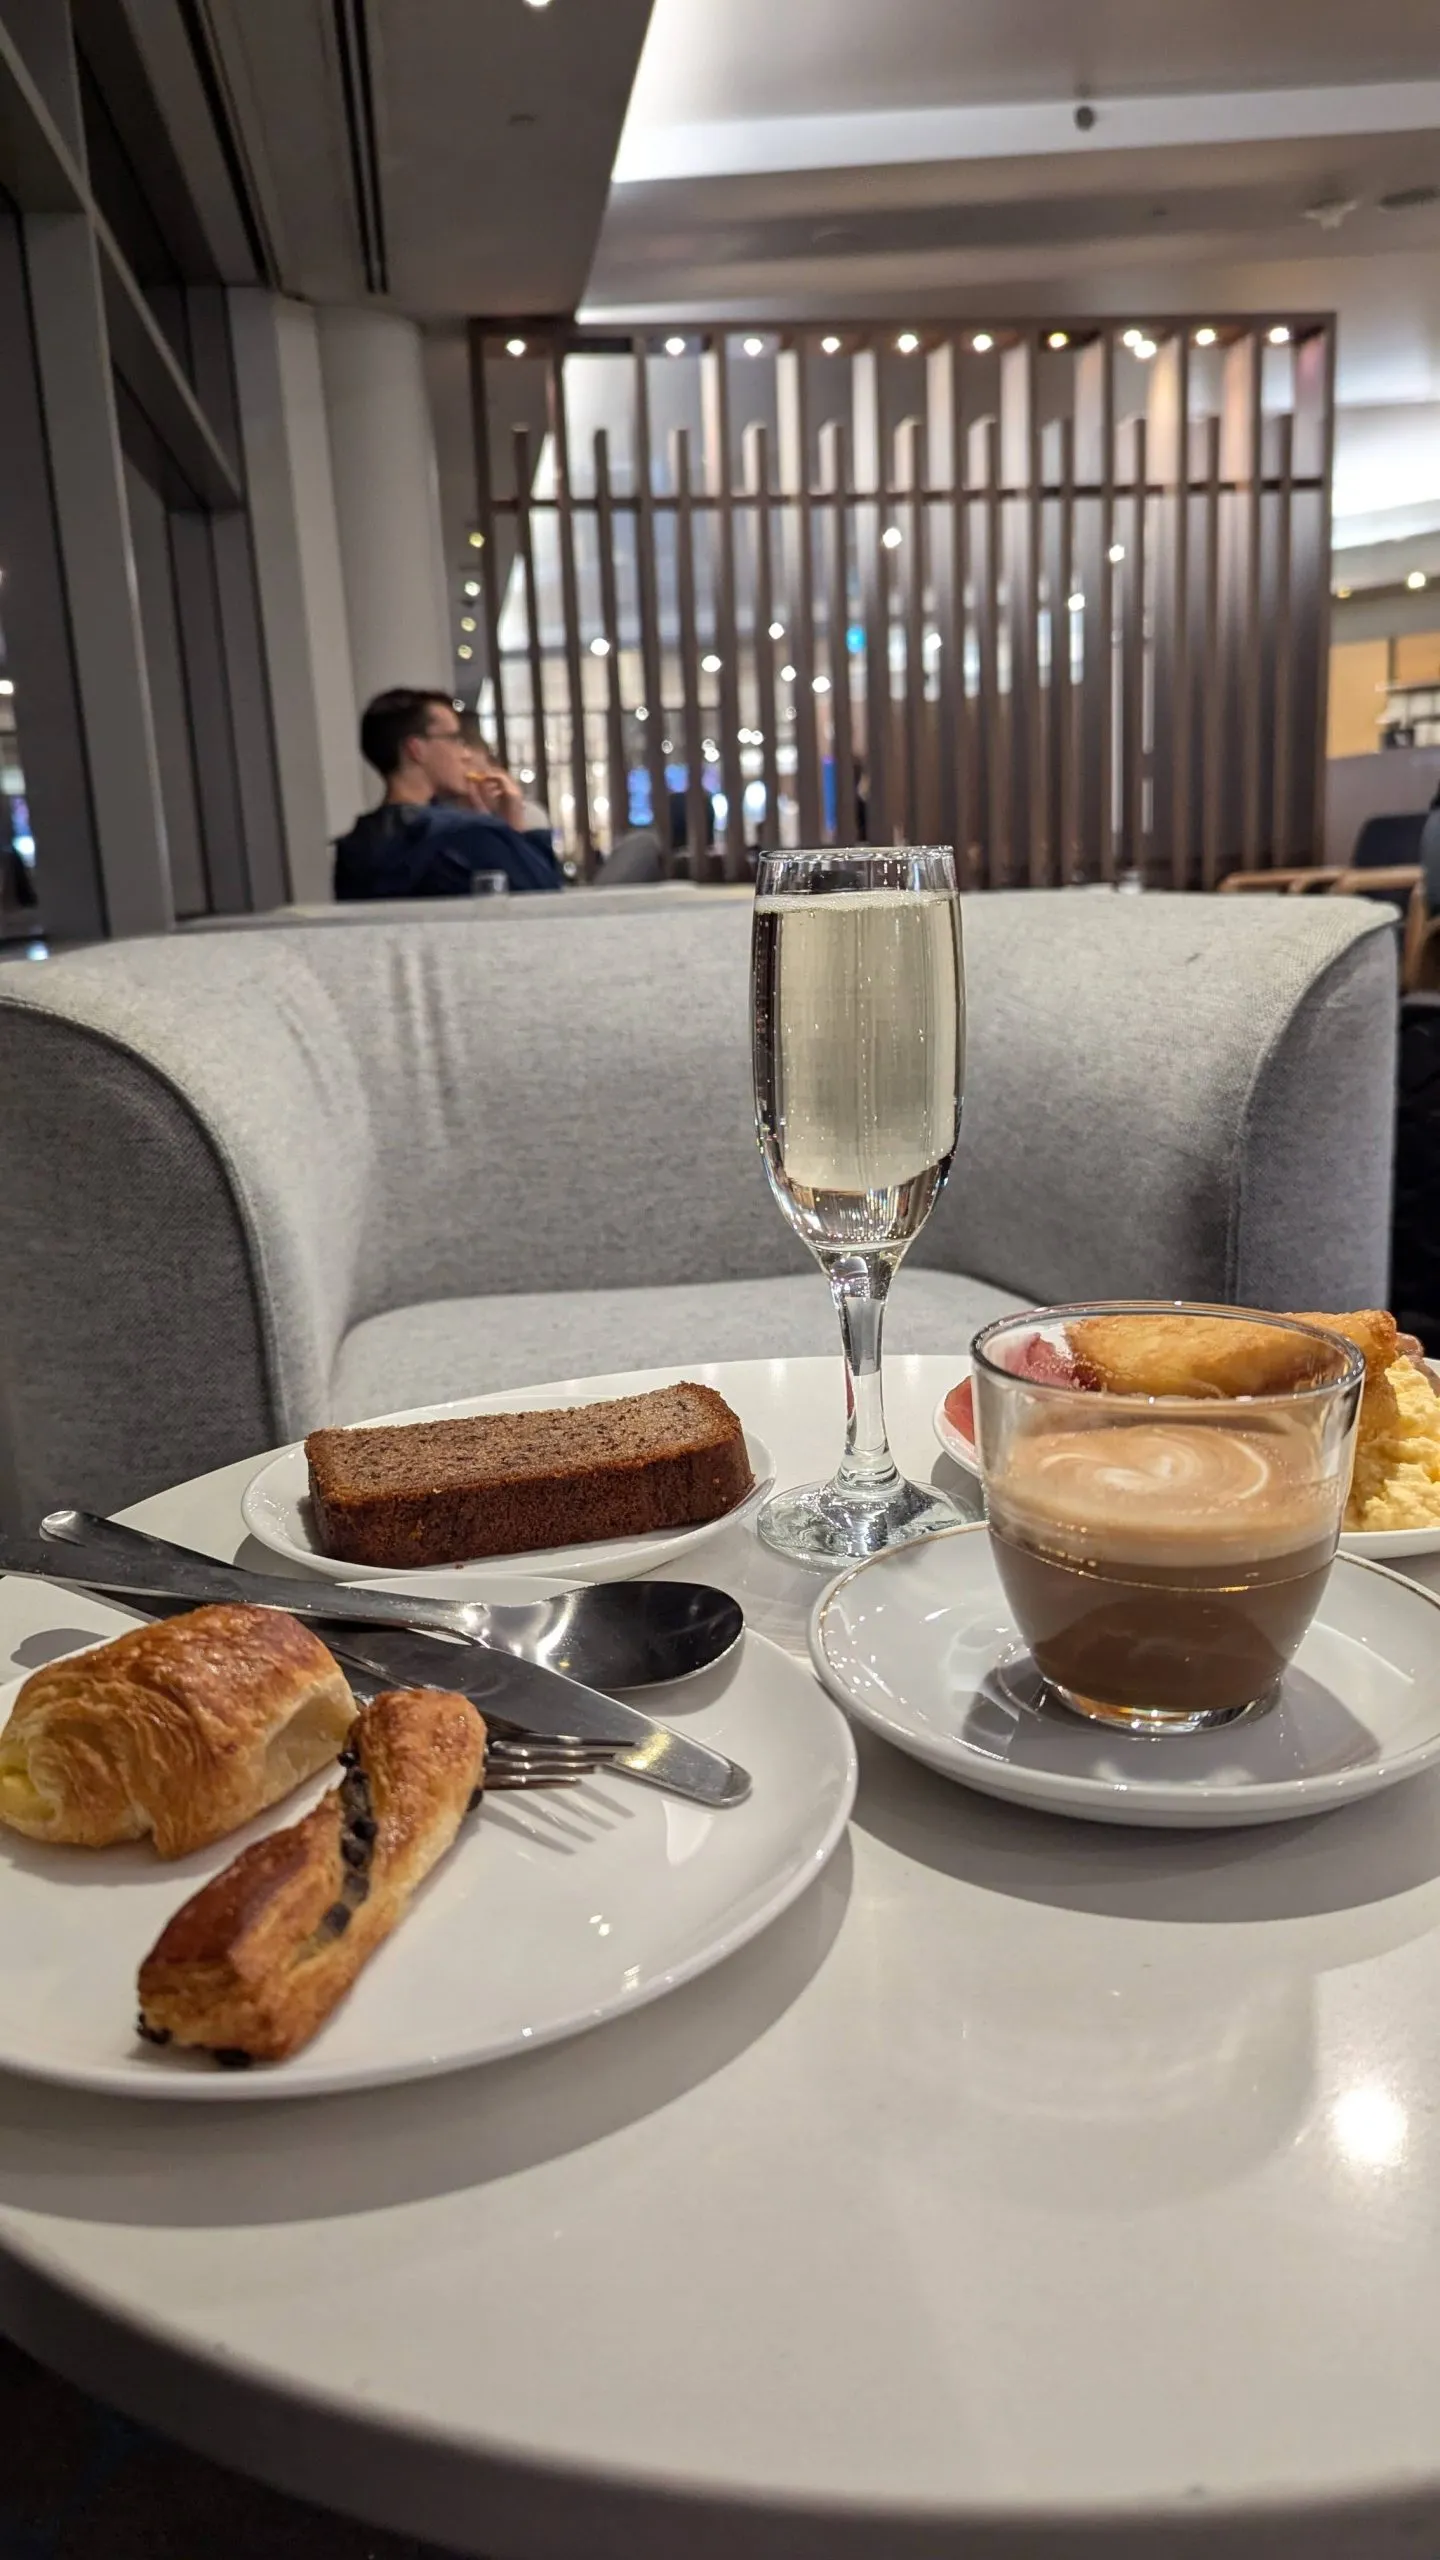
- The promise: two free passes to the Qantas Club.
- The reality (the “invitation” trap): These are “invitations”, not passes, and that’s a critical distinction. You must log in and link them to a flight at least 24 hours in advance. You’re the lowest priority for entry and can (and will) be turned away if the lounge is busy.
- Our value: $100, if you can use them.
Perk 2: the “discounted” companion fare
- The promise: save up to 20% on a companion flight.
- The reality (the restriction trap): This is one of the most restrictive perks on the market. It’s domestic only, must be booked through a special Qantas Money portal, and the discount applies only to the base fare, not taxes. The 10% discount on the cheapest Red e-Deal fares is basically worthless.
- Our value: $0–$50, in a very specific, rare scenario.
Perk 3: complimentary travel insurance
- The promise: free travel insurance, underwritten by Chubb.
- The reality (the points-booker’s trap): The policy only applies once activated, and to activate it you must pay the full amount of a return ticket on the card. If you book a Qantas Classic Flight Reward with points and pay only the taxes and fees on this card, you are not insured. That’s a fatal flaw for a Qantas co-brand card.
- Our value: $0. Don’t rely on it.
| Total reliable value from perks | Ongoing annual fee |
|---|---|
| About $100 | $399 |
Ouch.
One more trap: the 0% balance transfer
The card offers a 0% p.a. introductory balance transfer. Sounds good?
The trap: the fine print says you’ll be “charged interest on retail purchases while you have a Balance Transfer”. The moment you use the 0% offer, you lose your interest-free period on all new purchases. You can’t use this card for points-earning and debt consolidation at the same time.
How it stacks up: the competition
This card’s biggest rival is the Qantas American Express Ultimate.
| Qantas Amex Ultimate | Qantas Money Platinum | |
|---|---|---|
| Annual fee | $450 | $399 (ongoing) |
| Qantas travel credit | $450 every year | $0 |
| Net annual fee | $0 for anyone who flies Qantas at least once | $399 |
| Base earn rate | 1.25 points per $1 (1 point after 100,000 points a year) | 1 point per $1, soft cap |
The Qantas Money Platinum’s only advantage here is that Mastercard is accepted in more places. For ongoing value, the Amex beats it hands down.
Our final verdict: who should (and shouldn’t) get this card?
At All Points No Status, our job is to find the real value and cut through the marketing fluff. Here’s our recommendation.
Get this card if:
- You’re a first-year newbie who can get the full 80,000-point bonus. That’s the number one reason to get it.
- You’re Amex-averse and need a Mastercard for high domestic spend (that $10k monthly soft cap is good!).
- You plan to cancel or downgrade it in year two, when the $399 fee hits.
Avoid this card if:
- You travel internationally. That 3% foreign transaction fee is a deal-breaker and makes the international earn rate a net loss.
- You book with points and need reliable travel insurance. This policy is a trap.
- You want a simple set-and-forget card. The $399 ongoing fee isn’t worth the perks, so look at the Qantas Amex Ultimate instead.
- You ever carry a balance. The 20.99% interest rate will destroy any points value you’ve earned.
This is a classic first-year powerhouse with a major second-year problem. Compare it with the other Qantas-earning options in the ultimate guide to Qantas points cards, or with a flexible alternative in our top 3 cards for beginners.
Want more reviews that tell you the truth about points? Follow @allpointsnostatus on Instagram for more ways to travel better for less.